

Balance sheet: Definition, examples and how to prepare one
Key Takeaways
- A balance sheet shows your business’s assets, liabilities, and owner’s equity, providing a snapshot of its financial position at a specific time.
- The balance sheet formula, Assets = Liabilities + Owner’s Equity, shows how business assets are funded and helps verify accurate financial records.
- To prepare a balance sheet, gather financial records, list assets, liabilities, and equity, calculate totals, and confirm both sides balance.
- Reading a balance sheet helps you understand your financial position by evaluating available assets, debt levels, owner’s equity, and working capital.
- Comparing balance sheets over time can reveal important financial trends, including whether assets and equity are growing or debt is increasing.
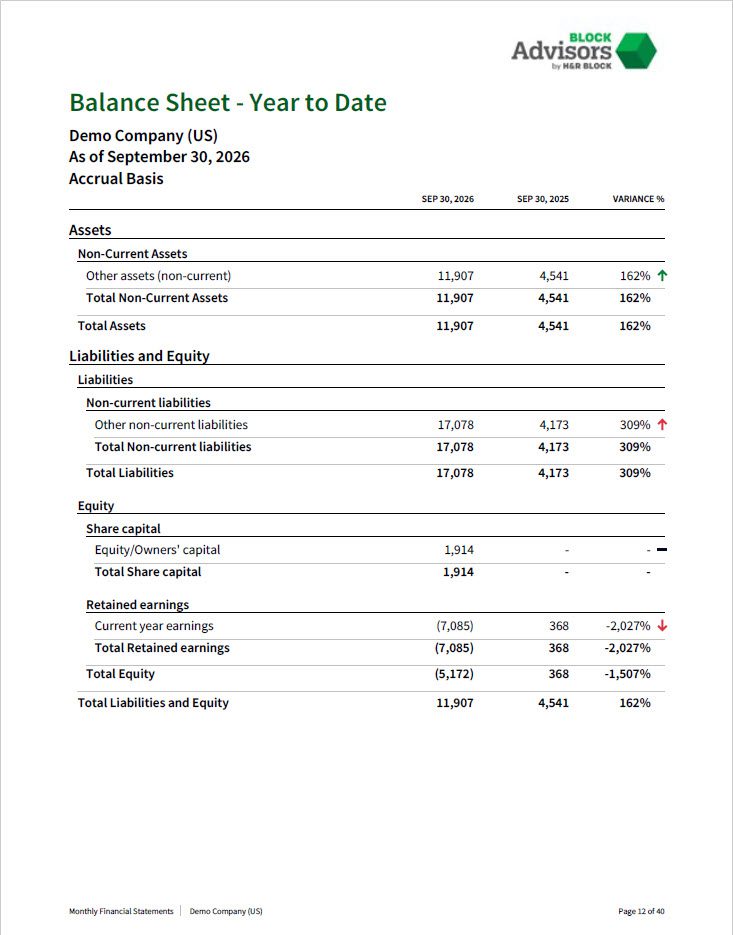
A balance sheet is a financial statement that shows what your business owns and what it owes at a specific point in time. Specifically, it lays out your assets (cash, inventory, equipment), your liabilities (loans, accounts payable), and your owner’s equity—the difference between the two.
For small business owners, a balance sheet is a useful tool for understanding your financial health at a glance. It tells you whether you have enough assets to cover your debts, how much of your business you truly own versus how much is financed by others, and whether your business is growing or shrinking over time.
This guide walks you through everything you need to know about a small business balance sheet. And if you need help with creating a balance sheet, we’re here to help.
Is balancing your small business books stressful?
We have starter and full-service options to grow with your small business
Who needs a balance sheet?
Any business—from a solo freelancer to a growing company with dozens of employees—can benefit from a balance sheet.
Here’s how different businesses use them:

- Sole Proprietorships use a balance sheet to track financial health, monitor debt levels, and make informed decisions about spending, hiring, or expansion.
- LLCs and partnerships need balance sheets to understand each owner’s equity share and to prepare accurate tax filings. They also use it to monitor debt levels and make informed decisions.
- Corporations rely on balance sheets for shareholder reporting, tax compliance, and strategic planning.
- Lenders and investors often request a balance sheet before approving a loan or making an investment, because it shows whether your business can handle additional debt.
- Tax professionals use balance sheet information to prepare accurate business tax returns and identify potential deductions or red flags.
A balance sheet is simple way to catch problems early—like taking on too much debt or letting cash reserves dip too low—before they become serious.
What goes on a balance sheet?
A balance sheet has three main sections: assets, liabilities, and owner’s equity. Every line item on your balance sheet falls into one of these three categories. The exact items you’ll account for will depend on your business, but we’ve listed a few common ones below.
Let’s dive into the details of these categories.
Assets: What your business owns
Assets are everything your business owns that has value. They’re typically listed in order of liquidity—how quickly you can convert them to cash.
Assets fall into two categories:
Current assets are things you expect to use or convert to cash within one year:
- Accounts receivable (money customers owe you)
- Cash and cash equivalents (checking and savings accounts)
- Inventory (products you hold for sale or raw materials)
- Prepaid expenses (insurance, rent, or supplies paid in advance)
Non-current assets are longer-term resources:
- Intangible assets (patents, trademarks, copyrights)
- Long-term investments
- Property, plant, and equipment (buildings, machinery, vehicles, furniture)
When listing equipment and other fixed assets, you’ll typically show their current value after depreciation rather than what you originally paid for them.
Liabilities: What your business owes
Liabilities are everything your business owes to others, from the IRS to suppliers and more. Like assets, they’re split into two categories:
Current liabilities are debts due within one year:
- Accrued expenses (wages, taxes, or utilities you’ve incurred but haven’t paid yet)
- Accounts payable (money you owe suppliers)
- Customer prepayments
- Current portion of long-term debt (the amount of a long-term loan due this year)
- Dividends or interest payable
- Payroll that has accrued, but has yet to be paid out (called payroll liabilities)
- Short-term loans or lines of credit
Non-current liabilities are debts due more than a year out:
- Deferred tax liabilities
- Long-term loans (equipment loans, mortgages, multi-year business loans)
Listing liabilities separately by due date helps you see which obligations are pressing and which are further down the road.
Owner’s equity: Your ownership interest in the business
Owner’s equity—sometimes called shareholder’s equity or net worth—is what’s left after you subtract liabilities from assets.
For a small business, owner’s equity typically includes:
- Owner’s capital – the money you’ve invested in the business
- Owner’s draws or distributions – money you’ve taken out (these reduce equity)
- Retained earnings – profits you’ve kept in the business rather than withdrawing (a profit and loss statement can help you track those profits over time)
If your business is a corporation, owner’s equity may also include stock shares and additional paid-in capital from investors.
Balance sheet accounts
Balance sheet accounts, also sometimes called “permanent” accounts, classify and record transactions related to a company’s total assets, liabilities, and shareholder equity. The balances on these accounts are carried forward from year to year.
Common balance sheet account items for a small business include:
- Asset accounts: Cash, Accounts Receivable, Inventory, Equipment, Accumulated Depreciation
- Liability accounts: Accounts Payable, Accrued Liabilities, Short-Term Loans, Long-Term Loans
- Equity accounts: Owner’s Capital, Retained Earnings, Owner’s Draw
It’s worth noting that balance sheet accounts are different from income statement accounts (or “temporary” accounts), which store transactions related to yearly revenues and expenses. Income statement account balances are generally closed out and transferred to a balance sheet account at the end of each year when financial statements are compiled from the accounting records.
What is the balance sheet formula?
The balance sheet formula is Assets = Liabilities + Owner’s Equity
This formula, also called the accounting equation, is the foundation of double-entry bookkeeping. It means everything your business owns (assets) was paid for either by borrowing money (liabilities) or by the owner’s own investment and accumulated profits (owner’s equity). The two sides must always be equal.
Here you can see the balance sheet formula with a simplified example:
- Imagine your small bakery has $60,000 in total assets (cash, inventory, and equipment).
- You owe $30,000 in liabilities (a mix of accounts payable and a loan).
- Your owner’s equity should be $30,000 (the difference between what you own and what you owe).
The formula checks out: $60,000 = $30,000 + $30,000.
If the two sides don’t match, there’s an error somewhere in your records—a missing entry, a transposed number, or a misclassified account. That’s why the balance sheet formula is also a built-in accuracy check for your books.
How to prepare a balance sheet for a small business
Learning how to prepare a balance sheet for a small business is simpler than it might seem. Once you understand the three sections and the formula, the process is mostly about gathering your numbers and organizing them. Here’s how to make a balance sheet in three steps.
Step 1: Gather your financial records and choose a reporting date
Start by choosing the date—typically the last day of a month, quarter, or fiscal year. Then gather your financial records as of that date, including your bank statements, accounts receivable and payable reports, loan balances, inventory counts, and any records of owner contributions or withdrawals.
Step 2: List your assets, liabilities, and owner’s equity
Now it’s time to fill out the figures in your balance sheet. Start by listing every asset and its current value, separating current assets from non-current assets. Then list every liability, separating current from non-current. Finally, calculate your owner’s equity—the total of your owner’s capital plus retained earnings, minus any owner’s draws.
For each line item, pull the current account balance from your bookkeeping system. If you’re using accounting software, it may generate much of this automatically. If you’re doing it by hand or in a spreadsheet, make sure every number traces back to a source document like a bank statement, loan statement, or invoice.
Step 3: Calculate totals and check that your balance sheet balances
Add up your total assets, total liabilities, and total owner’s equity. Then verify that assets equal liabilities plus owner’s equity. If they match up, your balance sheet balances—and you can feel confident your numbers are accurate. If they don’t, go back through your records to find the discrepancy. Common culprits include a missing entry, a number entered in the wrong account, or an asset or liability you forgot to include.
Once everything balances, you have a complete small business balance sheet ready to use.
Small business balance sheet example
Let’s continue the hypothetical balance sheet example from earlier. Brianna’s Bakery is a small business owned by a single owner.
Here’s what the business’s balance sheet looks like as of December 31:
Assets
| Current assets | |
| Cash | $15,000 |
| Accounts receivable | $8,000 |
| Inventory | $12,000 |
| Total current assets | $35,000 |
| Non-current assets | |
| Equipment (net of depreciation) | $25,000 |
| Total non-current assets | $25,000 |
| Total assets | $60,000 |
Liabilities
| Current liabilities | |
| Accounts payable | $7,000 |
| Short-term loan | $5,000 |
| Total current liabilities | $12,000 |
| Non-current liabilities | |
| Long-term loan | $18,000 |
| Total non-current liabilities | $18,000 |
| Total liabilities | $30,000 |
Owner’s equity
| Owner’s capital | $20,000 |
| Retained earnings | $10,000 |
| Total owner’s equity | $30,000 |
| Total liabilities + owner’s equity | $60,000 |
As you can see, total assets ($60,000) equal total liabilities ($30,000) plus owner’s equity ($30,000). The balance sheet balances.
How to read a balance sheet
Knowing how to read a balance sheet is just as important as knowing how to prepare one.
Here’s what to look for:
- Check that it balances. The first thing to confirm is that total assets equal total liabilities plus owner’s equity. If it doesn’t, your numbers need another look before you draw any conclusions.
- Compare current assets to current liabilities. This tells you about your short-term financial health. In our Brianna’s Bakery example, current assets are $35,000 and current liabilities are $12,000. That means the business has $23,000 in working capital—the cushion available to cover day-to-day operations and near-term obligations. A healthy working capital figure means you can comfortably pay your bills; a negative or thin figure is a warning sign.
- Look at your debt levels. Total liabilities tell you how much your business owes. In the example, Brianna’s Bakery has $30,000 in total liabilities against $60,000 in assets—a debt-to-asset ratio of 50%. That means half of the business’s assets are financed by debt. A lower ratio generally means less risk, while a higher ratio suggests the business is heavily reliant on borrowed money.
- Review owner’s equity. Owner’s equity shows how much of the business you truly own. In the example, the owner has $20,000 in contributed capital and $10,000 retained earnings —profits the business has earned and kept rather than paying out. Growing retained earnings over time is a positive sign that your business is profitable and reinvesting in its future.
- Compare balance sheets over time. A single balance sheet is a snapshot. The real insight comes from comparing balance sheets from different periods. Are your assets growing? Is your debt shrinking? Is owner’s equity increasing? These trends tell you whether your business is heading in the right direction.
Reading a balance sheet regularly helps you spot issues early—like taking on too much debt or letting cash reserves run low—and make smarter decisions about spending, borrowing, and investing in your business.
Get help with creating a balance sheet and other small business tasks
If all of this sounds too complex, let Block Advisors help. We’re a team of experienced tax, bookkeeping, and payroll professionals dedicated to helping small businesses like yours.
We get that small business owners may not have the time or expertise to crunch numbers. Here’s where Block Advisors can help lighten your load. We offer tax, bookkeeping, and payroll services to help you get back to what you love.
Balance sheet FAQs
How often should a small business update its balance sheet?
Most small businesses should update their balance sheet monthly so they can monitor cash, debt, and equity consistently. At minimum, prepare one at the end of each quarter and fiscal year, as well as before applying for financing or making a major business decision.
Why doesn’t my balance sheet balance?
Common errors that cause a balance sheet not to balance include missing transactions, items that are duplicated, entered for the wrong amount, or assigned to the wrong account. Check that beginning balances are correct, each transaction has matching debits and credits, and net income and owner transactions are reflected properly in equity.
Can a small business have negative equity on its balance sheet?
Yes. Negative equity occurs when total liabilities exceed total assets. It can result from accumulated losses, substantial debt, or owner withdrawals and may signal financial strain, although the broader context and trend over time also matter.
Should personal assets and debts appear on a business balance sheet?
Generally, no. A business balance sheet should include only assets, liabilities, and equity that belong to the business. Keeping personal and business finances separate supports accurate records, but the correct treatment can depend on the business structure and transaction.
Can a business be profitable but still have a weak balance sheet?
Yes. Profitability reflects income and expenses over a period, while a balance sheet shows financial position at a specific date. A profitable business may still have limited cash, high debt, slow-paying customers, or too few assets to cover near-term obligations.
Does a new business need a balance sheet before making its first sale?
A new business can prepare a balance sheet before its first sale as a best practice, but it’s not required. This balance sheet may include startup cash, equipment, inventory, loans, unpaid bills, and the owner’s initial investment, giving the business a financial starting point.
Can I prepare a balance sheet if my bookkeeping records are incomplete?
You can create a preliminary balance sheet, but it may not be reliable until the missing records are reconciled. Gather bank and credit card statements, invoices, loan documents, inventory records, and owner transaction details, then correct or estimate amounts with support from a bookkeeping professional when needed.
Why is my bank balance different from the cash shown on my balance sheet?
The amounts may differ because of timing differences and unrecorded transactions, such as outstanding checks, deposits in transit, bank fees, or transfers. The cash balance on the balance sheet should match the adjusted book balance after a bank reconciliation, not necessarily the bank’s ending statement balance.
Should I use the same balance sheet date each month?
Yes. Using a consistent date, such as the last day of each month, makes period-to-period comparisons more meaningful. It also helps ensure that transactions are assigned to the correct reporting period.
What should I check before giving my balance sheet to a lender?
Confirm that assets equal liabilities plus equity, cash agrees with reconciled bank records, receivables and inventory are current, and all debts are included and classified correctly. Also check that the reporting date is clear, figures match supporting records, and the balance sheet is consistent with your income statement and tax filings.
This article is for informational purposes only. The content may not constitute the most up-to-date information and should not be construed as legal advice.